Goldman Sachs Slashes Tesla Q3 Delivery Estimate To 435,000
Wall Street analysts are recalibrating their expectations for Tesla as third-quarter delivery projections take a noticeable hit. Leading financial institution Goldman Sachs has officially revised its global delivery estimate for the electric vehicle manufacturer down to 435,000 units. The downward revision reflects emerging headwinds across key regional markets, signaling a potential slowdown in volume after a robust second-quarter rebound.
The updated figure represents a sharp reduction from the firm's previous forecast of 490,000 vehicles for the quarter. Furthermore, this revised estimate sits comfortably below the broader Wall Street consensus, which had previously pegged third-quarter deliveries at roughly 456,000 units. If these projections hold, the automaker will face a significant quarter-over-quarter volume retraction.
Sluggish Growth Across Key Electric Vehicle Markets
The primary driver behind the reduced outlook is softening demand in North America. In the United States, elevated interest rates and tighter consumer credit have created friction for buyers considering high-ticket purchases. Despite aggressive price adjustments and promotional financing packages offered throughout the summer, sales volumes in the region have tracked noticeably below earlier baseline expectations.
In China, the world’s largest electric vehicle arena, domestic competition continues to intensify. Local manufacturers are launching rival vehicles at lower price points while integrating localized digital features rapidly. This aggressive environment has squeezed market share for foreign brands, preventing the elevated growth trajectory previously anticipated for the third quarter across major Chinese metropolitan centers.
European sales have similarly faced friction due to broader macroeconomic cooling and reduced government electric vehicle incentives. Major markets across the continent have seen registered vehicle growth stall, contributing to the reduced forecast. These combined regional shortfalls have put substantial pressure on global delivery figures, overwhelming standard quarterly inventory absorption capacity.
Global Export Strategies Offset Core Regional Downturns
To mitigate the weakness in prime geographic territories, the manufacturer has pivoted toward high-growth secondary markets. Facilities such as Gigafactory Shanghai have increasingly focused on international exports to balance regional production capacity. Vehicles produced in China are now systematically routed toward emerging markets across Australia, Southeast Asia, and South America to maintain steady factory utilization.
Expanding into these developing EV regions provides a crucial relief valve for output capacity. In markets like Australia and Thailand, consumer adoption of battery-electric vehicles is accelerating from a lower base. Strong initial demand in these jurisdictions is expected to partially counter the delivery deficits observed in North America and Western Europe throughout the quarter.
However, reliance on international logistics introduces added complexities to end-of-quarter delivery timing. Shipping vehicles across oceans requires extended transit times, which can lead to delayed recognitions on balance sheets. As export volumes increase, managing quarter-end transit pipelines becomes critical to ensuring those vehicles are officially registered before reporting windows close.
Long-Term Financial Targets and Analyst Projections
Despite trimming short-term delivery numbers, financial analysts maintain a steady long-term perspective on the stock. Goldman Sachs analyst Mark Delaney reiterated a Neutral rating alongside a $360 price target for the company. The decision signals that while volume fluctuations pose near-term challenges, the automaker’s broader profitability structure and structural cost advantages remain intact relative to legacy automotive peers.
Analyst reports highlight software offerings as pivotal drivers for future enterprise value. The expansion and monetization of Full Self-Driving (FSD) technology are viewed as essential mechanisms to lift margins. Software-driven revenue models could decouple financial performance from raw hardware delivery counts, offering high-margin recurring income as autonomous capabilities advance toward broader commercial distribution.
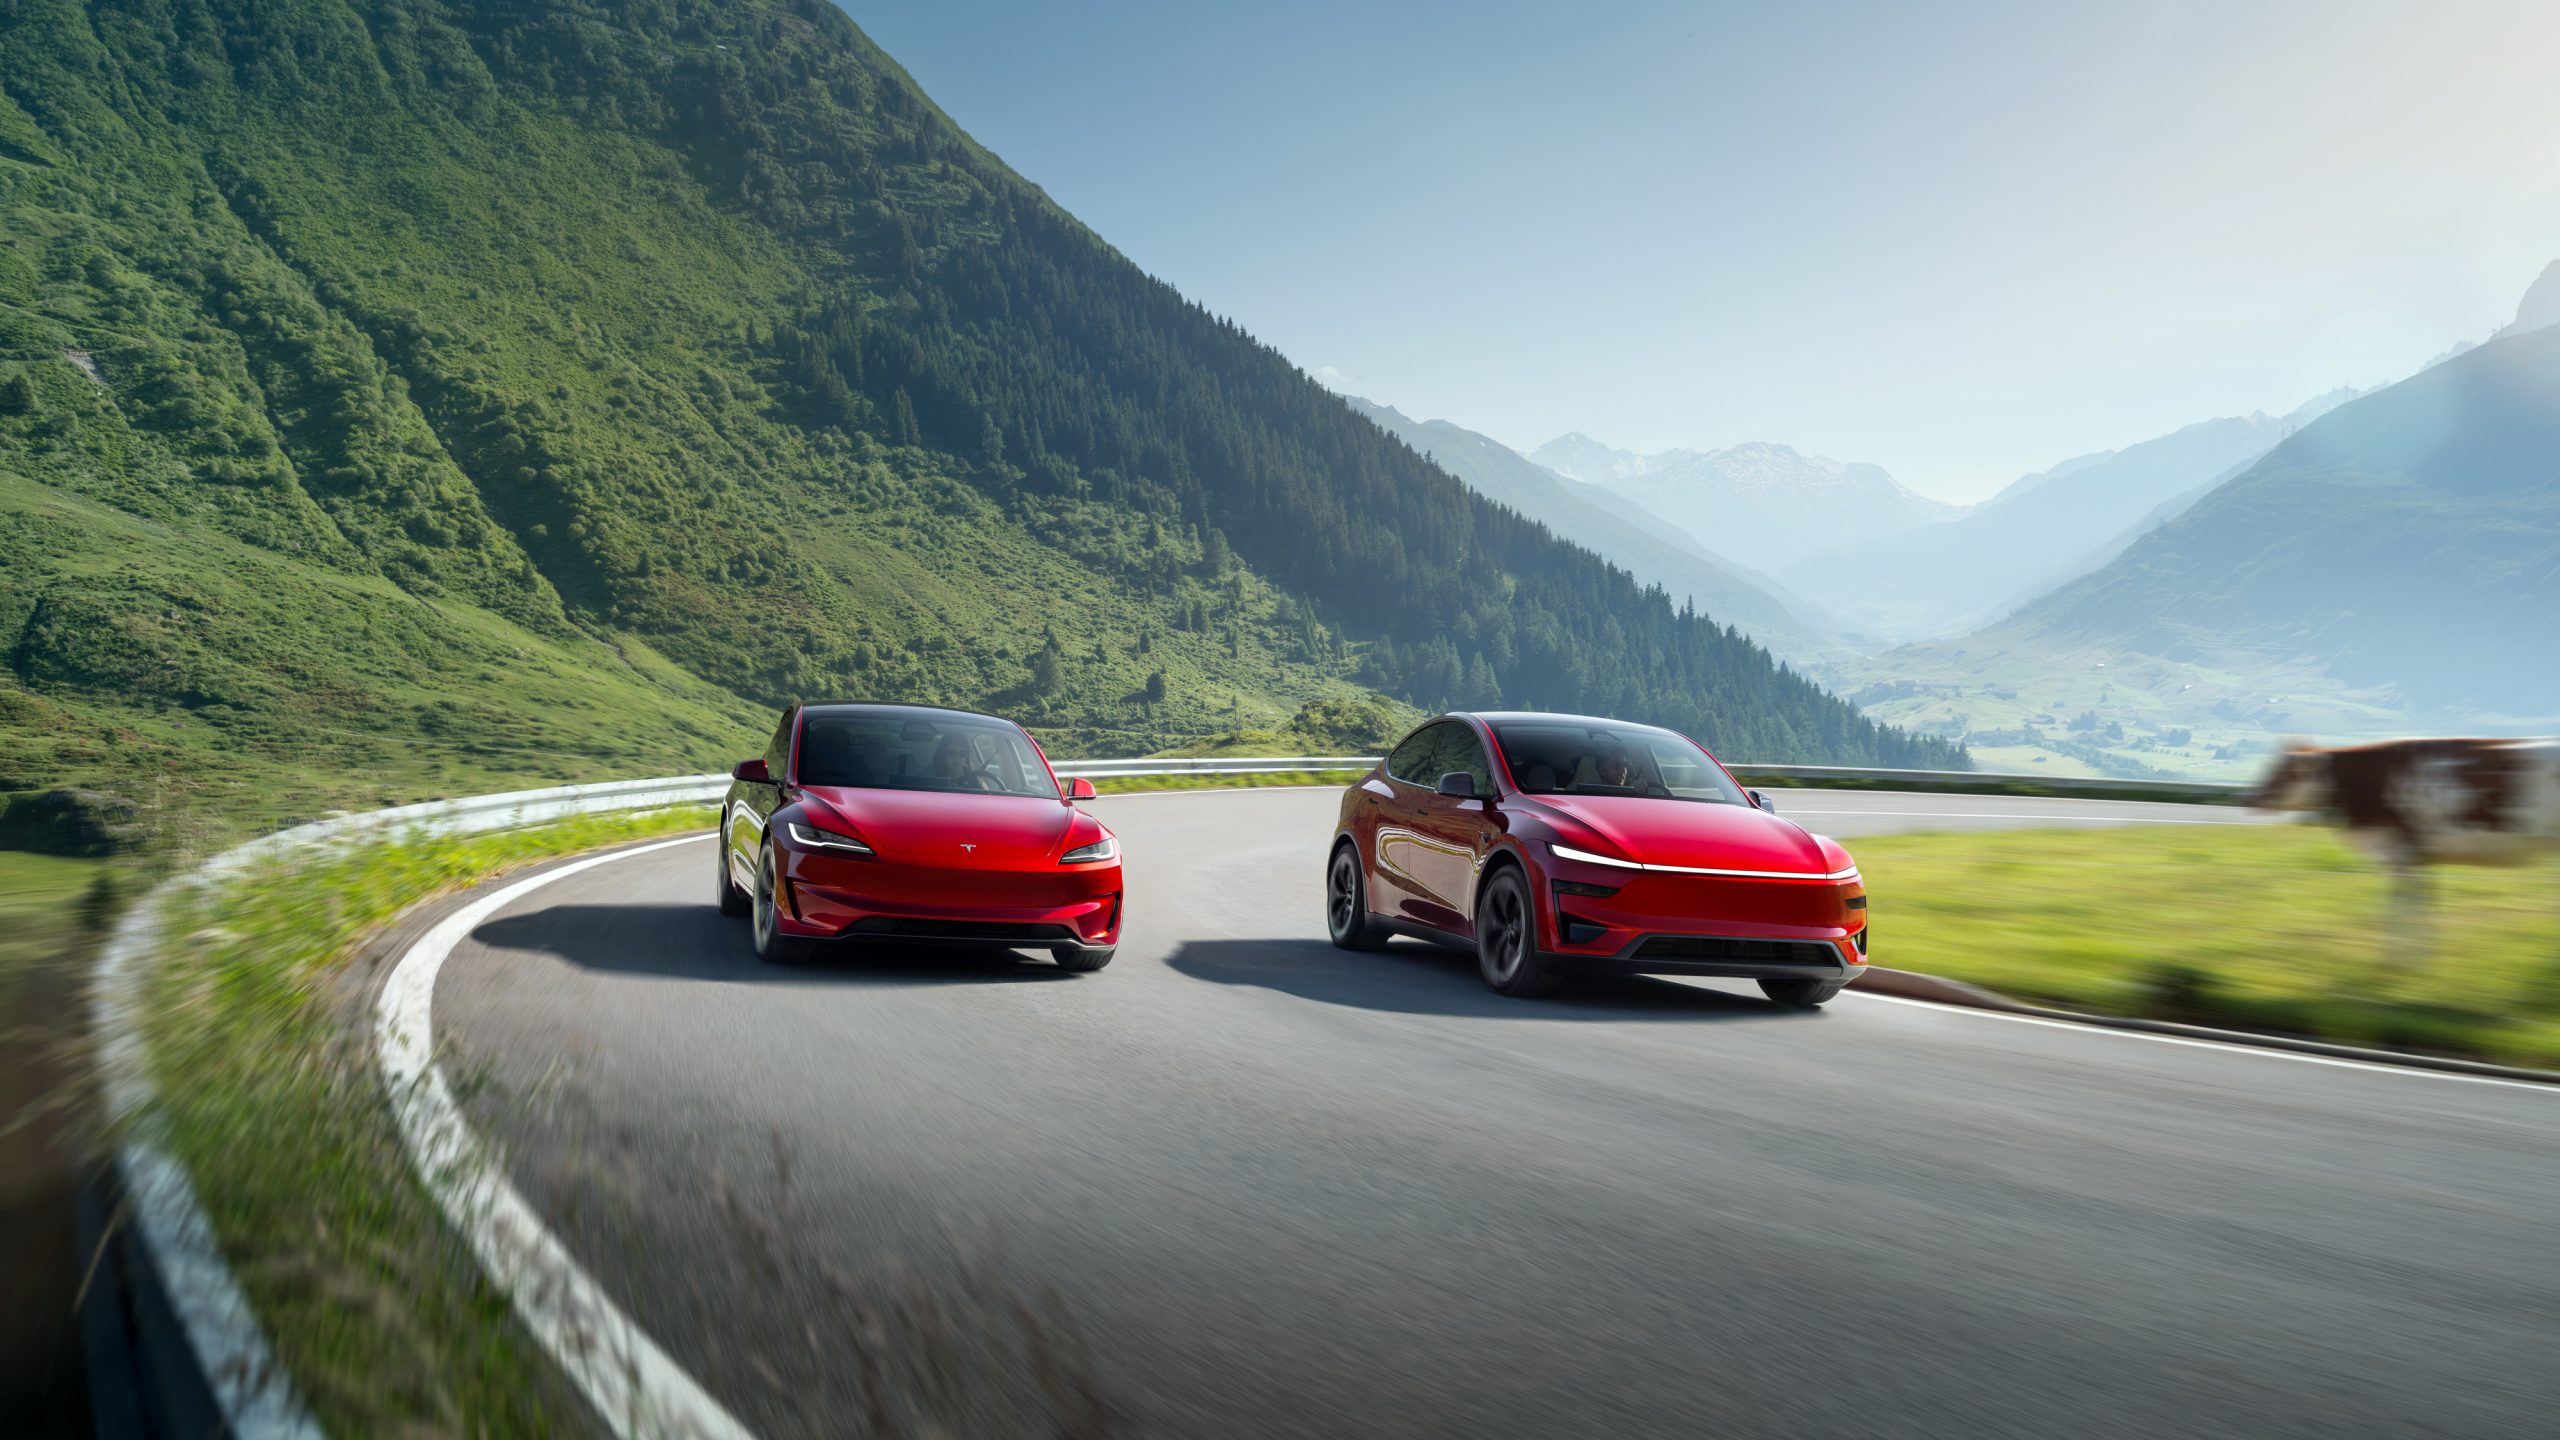
Product lineup refreshes are also expected to stimulate vehicle order volumes heading into the final quarter. The introduction of the six-seat Model Y L variant represents a strategic attempt to capture family-oriented buyers seeking expanded cabin space. Initial North American deliveries for this expanded configuration are scheduled to commence shortly, potentially reinvigorating consumer interest in the popular crossover segment.
Broader Implications for Tesla's Annual Deliveries
A delivery tally of 435,000 units would represent a 9 percent decline compared to the second quarter, when the company delivered 480,126 vehicles globally. That impressive second-quarter recovery, driven by 467,762 Model 3 and Model Y deliveries, had comfortably exceeded the first quarter’s slump of 358,023 units. A secondary dip highlights persistent demand volatility throughout the fiscal year.
Manufacturing lines have also undergone operational adjustments and brief retooling pauses, affecting global output consistency. Balancing factory output against fluctuating consumer demand requires precise operational management. As production lines stabilize, the company aims to optimize inventory levels across global distribution hubs to prevent costly oversupply situations in softening regional markets.
Market participants are now closely monitoring official production and delivery announcements expected in early October. The final metrics will confirm whether international exports successfully absorbed main market weakness or if macroeconomic headwinds proved more restrictive than anticipated. Industry stakeholders eagerly await these numbers to assess full-year guidance trajectories.
