May Mobility Goes Public via $1.4 Billion SPAC Merger Deal
Autonomous vehicle developer May Mobility has agreed to enter the public markets through a merger with a special purpose acquisition company, according to regulatory disclosures released this week. The transaction values the Ann Arbor-based autonomous platform creator at $1.4 billion and could yield over $300 million in gross cash proceeds to accelerate its commercial rollout across key metropolitan markets.
The business combination involves ACP Holdings Acquisition Corp., an entity sponsored by Houston-based investment firm Atlas Credit Partners. Upon closing of the merger, the company will list its shares publicly, marking a significant milestone for the broader autonomous driving sector after several years of consolidated funding rounds and selective strategic exits across the industry.
The strategic move presents public market investors with a distinct vehicle to gain direct financial exposure to robotaxi operations. Industry filings highlight that the resulting corporate entity will stand as the first U.S. public company focused exclusively on autonomous ride-hailing software and vehicle deployments, establishing a benchmark for pure-play autonomous mobility valuations.
A Pure-Play Bet on Autonomous Ride-Hailing
By focusing entirely on ride-hailing services, May Mobility creates a unique positioning strategy compared to its market peers. Major industry competitors such as Alphabet’s Waymo operate as subsidiaries within massive parent organizations, while Tesla and Rivian combine driverless initiatives with core electric vehicle manufacturing. Other publicly traded autonomy software firms focus predominantly on heavy-duty trucking applications.
This pure-play structure offers equity analysts and institutional investors an unhedged barometer for public market sentiment surrounding driverless passenger transport. Market observers note that while diversified tech giants can absorb the capital-intensive nature of autonomous development, pure-play entities face heightened scrutiny regarding operational efficiencies, milestone executions, and path-to-profitability timelines.
To navigate these capital demands, the enterprise seeks to separate software intelligence from physical fleet ownership. Rather than accumulating heavy balance sheet assets, the company plans to scale through collaborative transport ecosystems, leveraging existing fleet management infrastructure to accelerate geographical coverage without requiring massive capital investments in physical hardware.
Understanding the Asset-Light Business Model
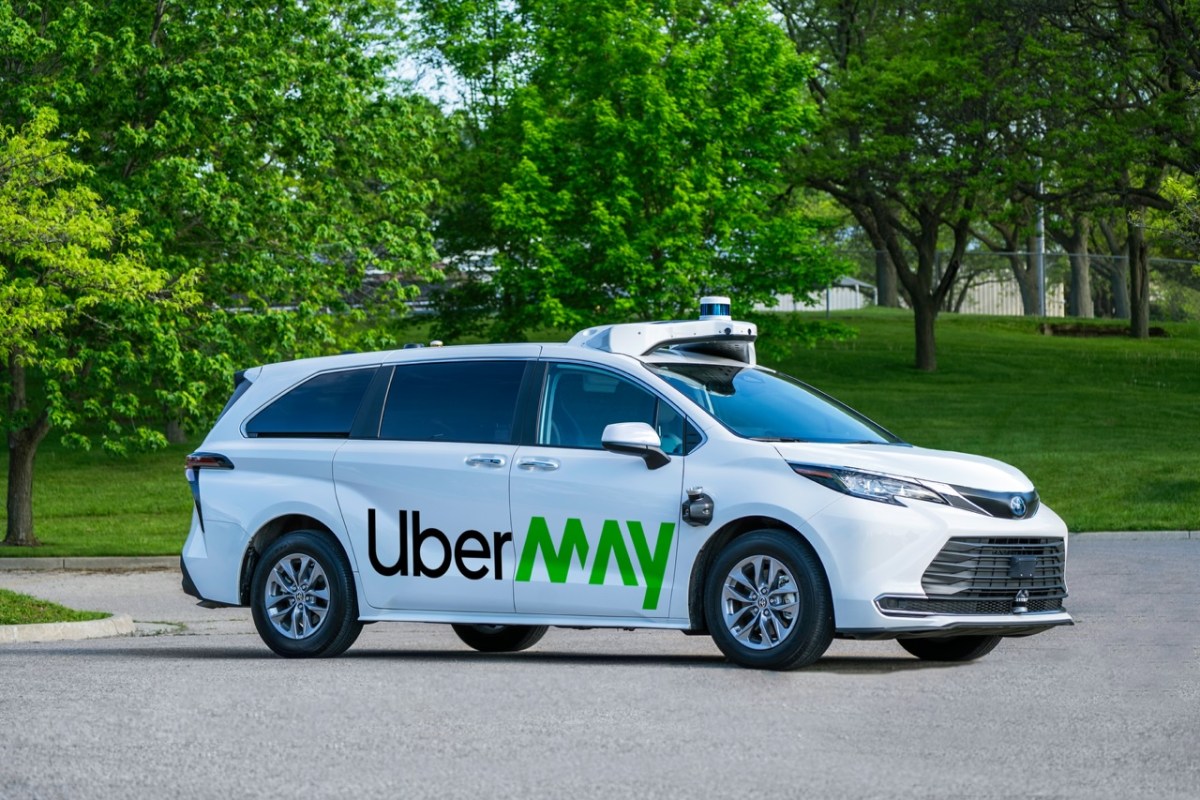
Central to May Mobility’s commercial pitch is an asset-light operational framework designed to mitigate traditional capital expenditures. Instead of owning and operating its vehicle fleets directly, the firm integrates its autonomous software and sensor suites into commercial platforms—such as specially modified Toyota Siennas—and sells those configured vehicles directly to fleet operations partners.
Once deployed, May Mobility maintains centralized control over remote vehicle oversight systems, mapping updates, and proprietary software maintenance. Revenue generation follows a hybrid monetization strategy, drawing income through fixed fleet management contracts or recurring per-trip software licensing fees. This approach transfers vehicle depreciation and localized maintenance costs onto operating partners.
Industry analysts point out that this partnership-first licensing framework closely mirrors traditional software-as-a-service structures. By insulating the core technology vendor from physical fleet maintenance liabilities, the model theoretically enables faster scaling into diverse municipal transit systems while retaining high-margin recurring software revenues as vehicle adoption rates increase globally.
Revenue Metrics and Current Operational Footprint
Founded in 2017, May Mobility has established active autonomous transit deployments across select municipal regions. Financial disclosures reveal that the company generated approximately $10 million in revenue during the previous fiscal year, operating alongside an annual cash burn of roughly $93 million as it invested heavily in system validation and technical engineering capabilities.
To date, the company has completed over 550,000 paid autonomous rides, logging more than 1 million commercial miles. Current operations include deployments in Minnesota, serving Grand Rapids and Eden Prairie, as well as an active integration alongside ride-hailing platform Lyft in Atlanta, Georgia, providing critical real-world validation for its technology stack.
Looking forward, the developer is actively expanding its international and domestic operational footprint. The enterprise recently initiated early trial testing in Japan and finalized plans for commercial fleet integrations with Uber in Arlington, Texas. That deployment is scheduled to commence commercial operations between late this year and early 2027.
Transaction Mechanics and Future Expansion Plans
The proposed public listing relies on a multi-tranche funding structure totaling over $300 million in prospective gross capital. The financing package includes a committed $120 million Private Investment in Public Equity transaction, alongside up to $217 million held within the trust account maintained by ACP Holdings Acquisition Corp.
However, the ultimate net capital delivered to the company remains heavily contingent upon shareholder redemption rates typical of special purpose acquisition deals. Capital redemptions by public SPAC shareholders prior to closing could reduce the cash transferred to the balance sheet, a variable that executive management must carefully manage.
According to transaction documentation, May Mobility plans to allocate net proceeds toward advanced software research and development, specifically targeting the removal of human safety drivers from active commercial routes. Additional funds will target bill-of-materials cost reductions and supply chain optimization, alongside expanding commercial routes into new target markets.
